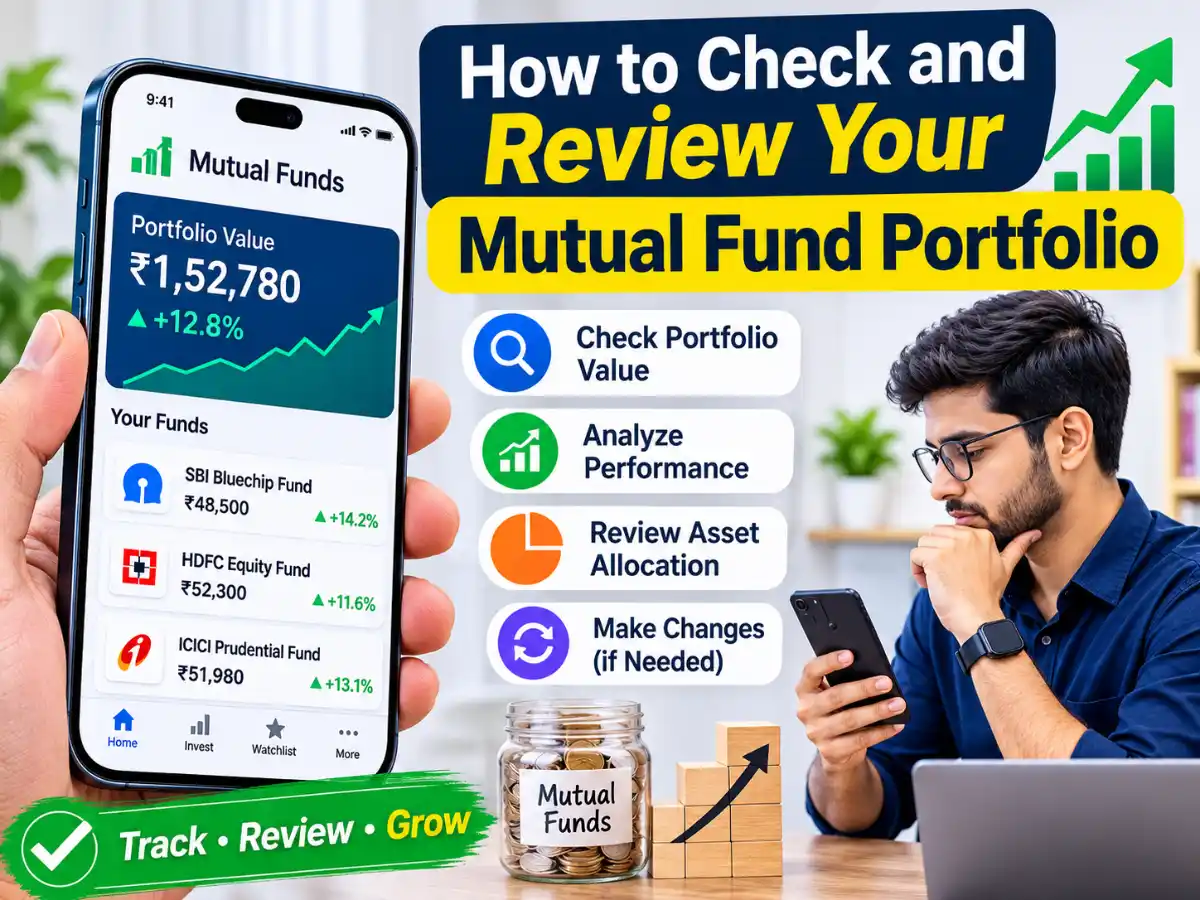
Quick answer: To check your mutual fund portfolio, download a Consolidated Account Statement (CAS) from MF Central, CAMS or KFintech using your PAN. It lists every fund you own across all fund houses. Then, before the financial year ends on 31 March 2027, work through 10 quick checks: book tax-free long-term gains, finish ELSS if you’re on the old tax regime, rebalance, step up your SIPs, and make sure every folio has a nominee and up-to-date KYC. Most of it takes one evening.
Last updated: 18 November 2026
For a detailed, step-by-step portfolio review method, see How to Review Your Mutual Fund Portfolio. This post is the year-end to-do list.
Step 0: check your full portfolio in 10 minutes
| Where | What you get | Best for |
|---|---|---|
| MF Central (PAN + OTP) | All folios with CAMS- and KFintech-serviced AMCs, downloadable CAS | The quickest complete view |
| CAMS or KFintech CAS (by email) | A detailed statement with every transaction | Tax and returns calculations |
| NSDL or CDSL CAS | Demat holdings plus mutual funds | If you hold any units in demat |
| Your investing app | Live values and XIRR | Day-to-day tracking, but only for funds bought through that app |
Download a detailed CAS covering this financial year. You’ll need it for several of the checks below. Step-by-step instructions are in How to Check All Your Mutual Funds by PAN.
The year-end checklist
| # | Check | Deadline | Time needed |
|---|---|---|---|
| 1 | List every fund, its goal and whether it’s still needed | Anytime | 15 min |
| 2 | Book long-term gains up to ₹1.25 lakh tax-free | 31 March | 15 min |
| 3 | Book losses to offset gains (if any) | 31 March | 10 min |
| 4 | ELSS for Section 80C (old tax regime only) | 31 March | 5 min |
| 5 | Rebalance your equity–debt mix | Anytime, ideally once a year | 20 min |
| 6 | Step up your SIPs for the new year | April | 5 min |
| 7 | Check for failed or forgotten SIPs | Anytime | 5 min |
| 8 | Nominee on every folio | Anytime | 10 min |
| 9 | KYC status, mobile, email and bank details | Anytime | 10 min |
| 10 | Move money out of equity for goals due within 2–3 years | Anytime | 10 min |
1. List every fund and its job
For each fund on your CAS, write one line: which goal it’s for, and when you’ll need the money. Any fund you can’t attach to a goal is a candidate to merge or exit. If you hold four or five similar large cap or flexi cap funds, check how much they overlap. See Mutual Fund Overlap and How Many Mutual Funds Should You Actually Own?
2. Use your ₹1.25 lakh long-term gains exemption
Long-term gains on equity funds up to ₹1.25 lakh per financial year are tax-free. The exemption doesn’t carry forward, so if you don’t use it by 31 March, it’s gone.
How: redeem units held for more than 12 months whose gain is close to ₹1.25 lakh, then reinvest the same day or the next. Your cost price resets higher, so you’ll pay less tax when you finally sell. Watch the exit load (usually nil on units over a year old). More in LTCG on Mutual Funds.
3. Book losses if you have gains to offset
If a fund is showing a loss and you’ve also made gains this year, selling it can reduce your tax. Short-term capital losses can be set off against both short- and long-term gains. Long-term losses can only be set off against long-term gains. Unused losses can be carried forward for 8 years, if you file your return on time. Only do this with funds you’re happy to exit or immediately buy back.
4. ELSS, only if you’re on the old tax regime
ELSS investments count towards the ₹1.5 lakh Section 80C limit, but only under the old tax regime. The new regime, which is now the default, doesn’t allow 80C. Check which regime you’ll choose before investing for tax. Each ELSS instalment is locked in for 3 years. See ELSS vs PPF vs NPS.
5. Rebalance your asset mix
After a strong year for equity, your portfolio may hold more equity than you planned. For example, a 60:40 equity–debt plan may have drifted to 70:30.
- Drift under about 5 percentage points: leave it.
- More than that: bring it back. First direct new SIPs towards the underweight side, which triggers no tax. Then, if needed, move money across and use your ₹1.25 lakh exemption.
6. Step up your SIPs for the new financial year
If your salary went up, raise your SIPs too, even by 10%. Over 20 years, that roughly doubles what a flat SIP builds. See Step-Up SIP vs Regular SIP.
7. Look for failed or forgotten SIPs
On your CAS, check that every SIP instalment actually went through. Failed bank mandates, closed accounts and old SIPs you meant to stop are common. Three failed instalments in a row can lead the fund house to cancel the SIP. See What Happens If You Miss SIP for 3 Months?
8. A nominee on every folio
Your CAS shows nomination status for each folio. Any folio without a nominee will be much harder for your family to claim. Adding one takes a few minutes online. See How to Change Nominee in a Mutual Fund.
9. KYC and contact details
Check that your KYC status is validated and that your mobile, email and bank account are current on every folio. Out-of-date details are the most common reason redemptions get stuck. See Mutual Fund KYC Online.
10. De-risk goals that are close
Money you need within 2–3 years, such as school fees, a home down payment or a wedding, shouldn’t be fully in equity. Move it gradually to liquid or short-duration debt funds, using an STP or staged redemptions. See What Is STP in Mutual Funds?
What NOT to do at year-end
- Don’t sell a fund just because it lagged for one year. Judge it on 3–5 years against its benchmark. See Why the Best-Performing Fund Is Often a Bad Choice.
- Don’t rush into an ELSS if you’re on the new tax regime. It saves you no tax there.
- Don’t let tax-saving decide your investments. A tax saving that leaves you in the wrong fund isn’t a saving.
- Don’t harvest gains on units under 12 months old. They’re taxed at 20% short-term.
Want help with the review?
RingMoney’s advisors can go through your CAS with you, flag overlapping funds and missing nominees, and suggest a rebalancing plan. Start in the app, or read about goal-based investing.
FAQs
How can I check my complete mutual fund portfolio?
Download a Consolidated Account Statement using your PAN from MF Central, CAMS or KFintech. It lists all your folios across every fund house.
How often should I review my mutual fund portfolio?
A full review once a year is enough for most people. Year-end (January to March) is a good time because of the tax deadlines. Glance at it quarterly.
When should I rebalance my mutual fund portfolio?
Once a year, or when your equity–debt mix drifts more than about 5 percentage points from your target.
What is the last date for tax-saving mutual fund investments this year?
31 March 2027 for FY 2026-27. Make sure the money reaches the fund house before the cut-off on the last business day.
Should I stop SIPs in funds that performed badly this year?
Not on one year’s performance. Compare the fund with its benchmark and category over 3–5 years before deciding.
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. RingMoney is an AMFI-registered mutual fund distributor (ARN-320453). Tax rules are as per current law and may change. This isn’t tax advice. Consult a tax professional for your situation.
Related reading: How to Review Your Mutual Fund Portfolio · LTCG on Mutual Funds · How to Check All Your Mutual Funds by PAN · Mutual Fund Terms (Glossary)