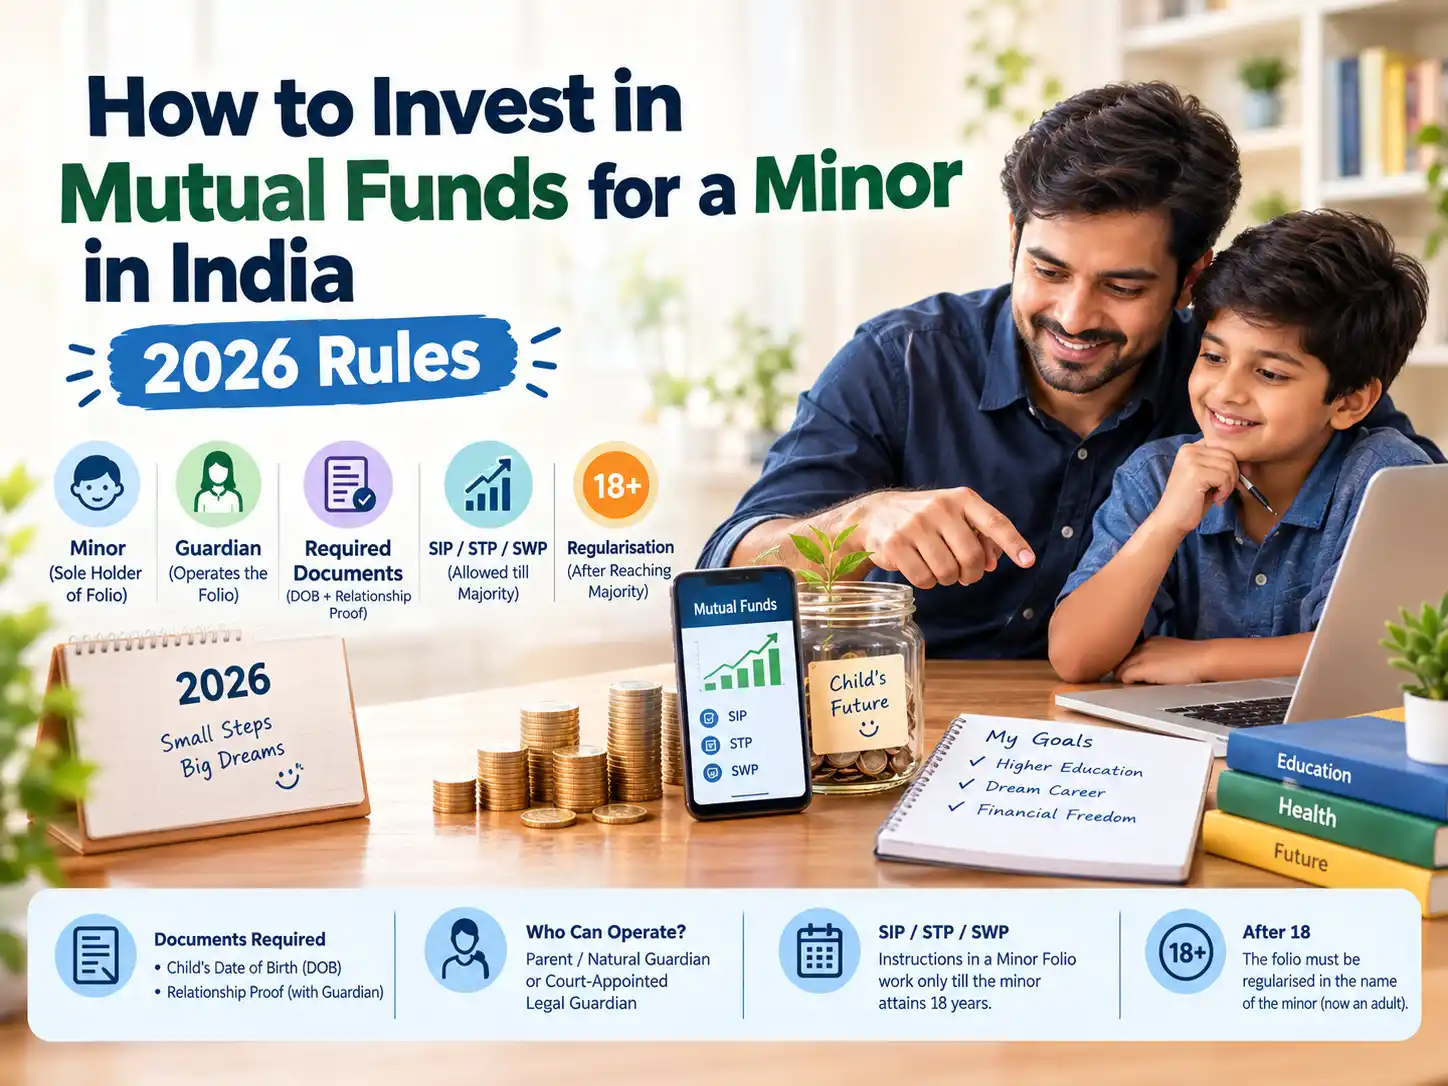
Quick answer: You can open a mutual fund folio in your child’s name with yourself (a parent) or a court-appointed guardian as the guardian. You’ll need the child’s date-of-birth proof, your KYC and PAN, and a bank account for redemptions in the child’s name. Since 15 June 2023, SEBI lets you pay from your own bank account, the child’s account or a joint account. The minor is the only holder and you can’t add a joint holder.
Plenty of parents start investing “for the child” in their own name. It works, but it gets messy later: the money mixes with yours, and nothing stops it being spent on something else. A minor folio ring-fences it.
Step-by-step: how to start a SIP in your child’s name
1. Collect the documents
- Child’s date-of-birth proof: birth certificate or passport.
- Guardian’s KYC: your PAN, Aadhaar and KYC must be in “Validated” or “Registered” status. Our KYC guide shows how to check.
- Proof of relationship if your name isn’t on the birth certificate, or a court order for a legal guardian.
- Child’s PAN: many fund houses and platforms now ask for it. Apply early (Form 49A, signed by the parent) so it doesn’t hold you up.
- A bank account in the child’s name (a minor account or a joint account with you). Redemption money can only go here.
What goes wrong: the child’s name is spelt differently on the birth certificate and the bank account. Fix it before you apply, or the folio gets stuck.
2. Choose the funds
Match the funds to the goal date, not to the child’s age: – Goal 10+ years away (graduation for a toddler): mostly equity, such as flexi cap or index funds, with an education goal plan. – Goal 5–10 years away: a mix of equity and hybrid. – Goal under 5 years away: move gradually to debt and hybrid funds so a market fall in the final year can’t wreck the fees.
What about “children’s funds”? Under SEBI’s 2026 rules, solution-oriented schemes (children’s and retirement funds) stopped taking fresh investments from April 2026 and are being merged into other categories. A plain flexi cap or index fund, labelled as your child’s goal, does the same job without the lock-in.
3. Set up the SIP
The folio is opened as Minor (first and only holder) + Guardian. Pay through a mandate on your account, the child’s account or a joint account. All three are allowed since June 2023.
4. Track it as a separate goal
Name it (“Aarav, college 2040”) so it never gets mixed up with your retirement money.
What happens when your child turns 18?
People skip this part, and it causes real hassle.
- SIPs, STPs and SWPs are suspended on the date the child turns 18, until the folio status changes from minor to major.
- Your child completes their own KYC and submits a “Change of status from minor to major” form, with their bank details and signature attested by the bank.
- After that, you as guardian can no longer operate the folio. The money is legally theirs.
Tip: put a reminder in your calendar for 3 months before the 18th birthday. Getting KYC and the form ready early means the SIP restarts without a gap.
How are a minor’s mutual fund gains taxed?
Under the clubbing rules, income and capital gains from investments in a minor’s name are added to the income of the parent who earns more (or the parent who holds custody, in some cases) and taxed at that parent’s rates. There’s a small exemption of ₹1,500 per child per year.
So a minor folio doesn’t save tax. It ring-fences money. Two exceptions: – Income from the child’s own skill or work, such as acting, sport or art, isn’t clubbed. – Once the child turns 18, gains are taxed in their own name, usually at a much lower slab. Booking long-term gains after 18 can save tax, and every adult gets the ₹1.25 lakh equity LTCG exemption separately.
Minor folio rules at a glance
Question | Answer |
|---|---|
Can I add a joint holder? | No. The minor is the sole holder. |
Can I add a nominee? | No. Nomination isn’t allowed in a minor folio. |
Who can pay? | The minor’s, parent’s or guardian’s bank account, or a joint account (since June 2023). |
Where do redemptions go? | Only to the minor’s bank account. |
Can grandparents invest? | They can gift money, but the guardian must be a parent or a court-appointed guardian. |
Is there a lock-in? | No, except in ELSS (3 years). |
Minor folio vs investing in your own name
Minor folio | Your own name | |
|---|---|---|
Money ring-fenced for the child | Yes | No |
Tax | Clubbed with parent | Taxed with you |
Control after 18 | Child’s | Yours |
Flexibility to use for another goal | Low | High |
Paperwork | Slightly more | Less |
If you want full control (for example, you’re not sure how mature your child will be at 18), invest in your own name and label the goal clearly. If you want the money to be unmistakably your child’s, use a minor folio.
Frequently Asked Questions
Can I start a SIP in my child’s name without the child’s bank account?
You can pay from your own account, but the folio still needs a bank account in the child’s name registered for redemptions.
Is a PAN card mandatory for a minor to invest in mutual funds?
Requirements differ between platforms, but most now ask for the minor’s PAN. Getting one avoids delays.
What age is best to start a SIP for a child?
As early as possible. A ₹5,000 monthly SIP started at birth has 18 years to compound. See what ₹5,000 a month can grow to.
Can I use my child’s mutual fund for my own expenses?
Legally the money belongs to the child, and redemptions go only to the minor’s account. Treat it as theirs.
Which funds are best for a child’s education?
For goals 10+ years away, diversified equity (flexi cap or index funds), shifting to hybrid and debt in the last 3–5 years.